Most of us know a big bill will turn up sooner or later. What we cannot know is when, or whether there will be enough in the bank to cover it. When the money is not there and the problem will not wait, some people borrow against their car.
These are five of the costs we see most often at Logbook Money. For each one we have added a few things worth checking before you borrow, because the best fix is sometimes not a loan at all.
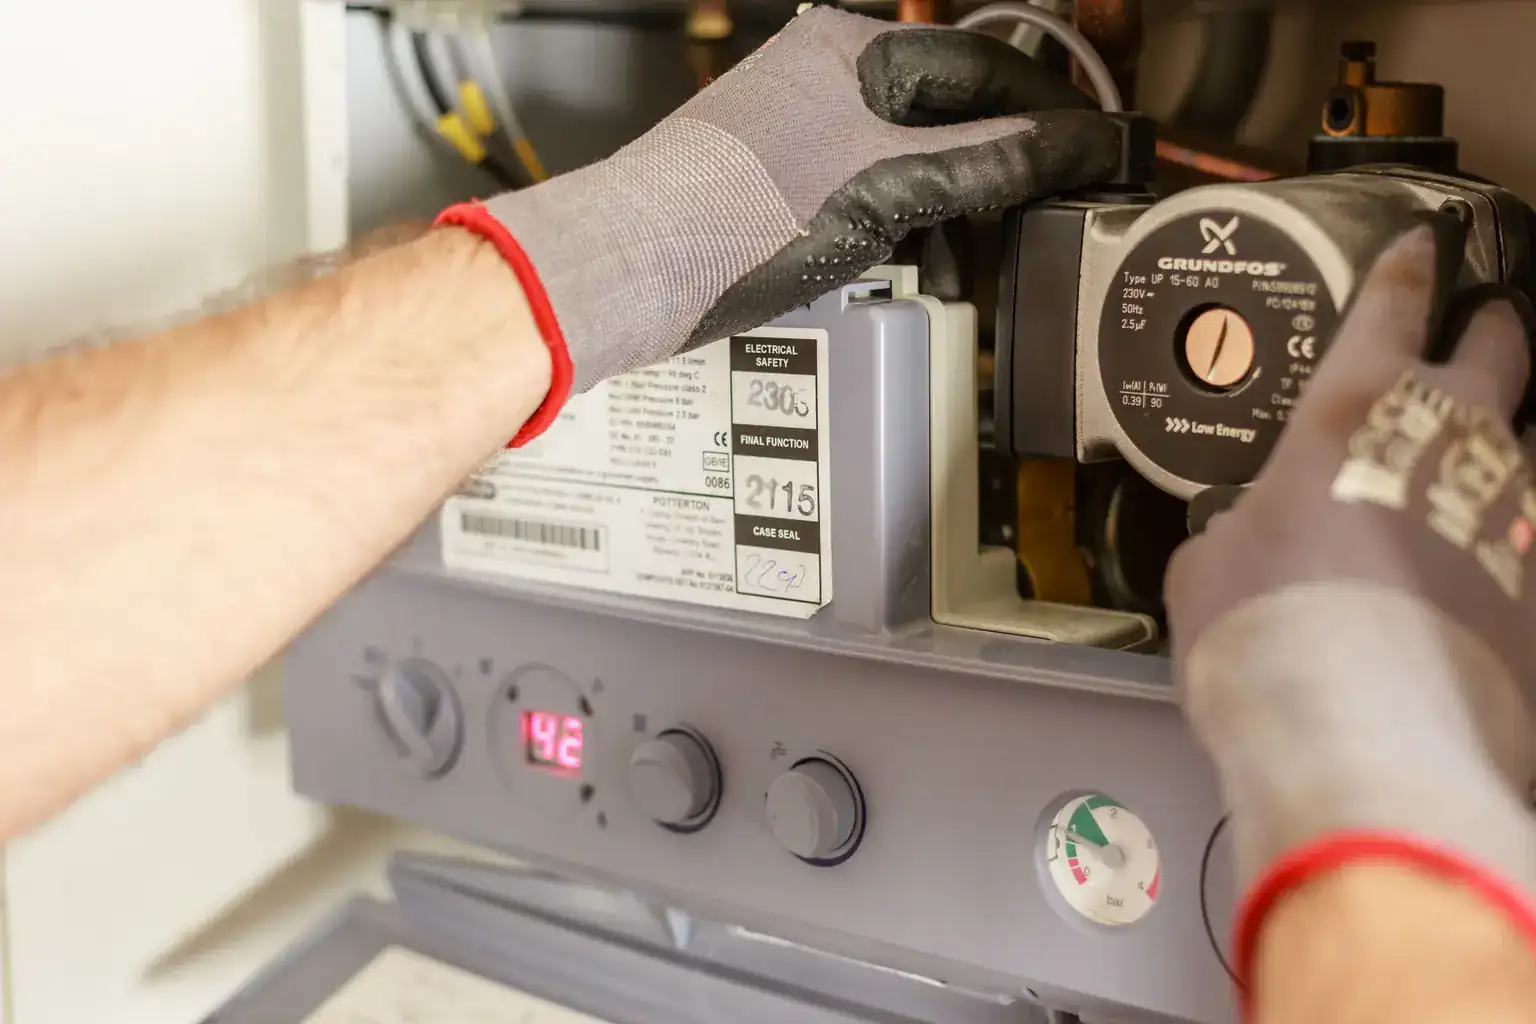
1. A boiler that breaks down
No heating or hot water is miserable at any time of year, and a real worry if you have young children or someone unwell at home. Repairs can be expensive, and a full replacement more so.
Check first:
- If you rent, boiler repairs are normally your landlord's job, so tell them straight away and put it in writing.
- Look through your home insurance and any boiler cover plan. Home emergency cover is sometimes included without people realising.
- Get more than one quote, and only let a Gas Safe registered engineer work on a gas boiler.
2. Repairs to the car you rely on
If you need your car to get to work, a breakdown can put your income at risk as well as your plans for the week. Garage bills for a clutch, gearbox or timing belt can mount up quickly.
See whether the repair is covered by a warranty or, after an accident, by your insurer. If the car that needs fixing is the one you would borrow against, talk to us first. To secure a loan, a vehicle has to be in good mechanical and cosmetic order with valid tax, MOT and insurance. You can see which vehicles we accept, including vans and motorbikes.
3. Damage to your home
A leaking roof, a burst pipe or storm damage tends to get worse the longer it is left. Water gets into walls and floors, and a small job turns into a big one.
Before borrowing, ring your buildings insurer, as storm and water damage are often covered, though you may have an excess to pay. Take photos before any work starts. If you rent, report it to your landlord, who is usually responsible for the structure of the property.
4. A bill that has to be paid now
Sometimes it is not a breakdown but a demand: a large council tax bill, an energy catch-up payment or a final reminder with a deadline on it.
This is where borrowing needs the most thought. Many organisations will agree a payment plan if you contact them early. Energy suppliers are expected to offer arrangements you can afford, and councils can often spread arrears. If you are juggling several bills, a free adviser at StepChange or National Debtline can help you work out which to deal with first. Taking on a secured loan to clear bills you are already struggling with can make things harder, not easier.
5. Bridging a short gap in income
A new job that pays monthly in arrears, a late contract payment or a few weeks between jobs can leave you short. People sometimes borrow to cover essentials until the money starts coming in again.
The big question is how sure you are that the gap really is temporary. A logbook loan runs for at least 18 months, so the repayments need to be affordable from your normal income, not just from the money you are waiting for. If you have some savings, using them instead is worth considering. Our article on using savings or borrowing walks through that decision.
Before you borrow against your car
If you do decide to borrow, keep the loan as small as you can. A logbook loan is a costly way to borrow, and your vehicle is at risk if you fall behind. Use our loan calculator to check the representative example and see what the repayments would be, and go through our questions to ask before taking a logbook loan. We only lend when the repayments are affordable for you. This article is general information, not financial advice. If your worries go beyond one bill, MoneyHelper and Citizens Advice offer free, impartial help.
Your car may be repossessed if you do not keep up repayments on a loan secured against it.





